Q3 2026 Investor Letter
Fellow Investors,
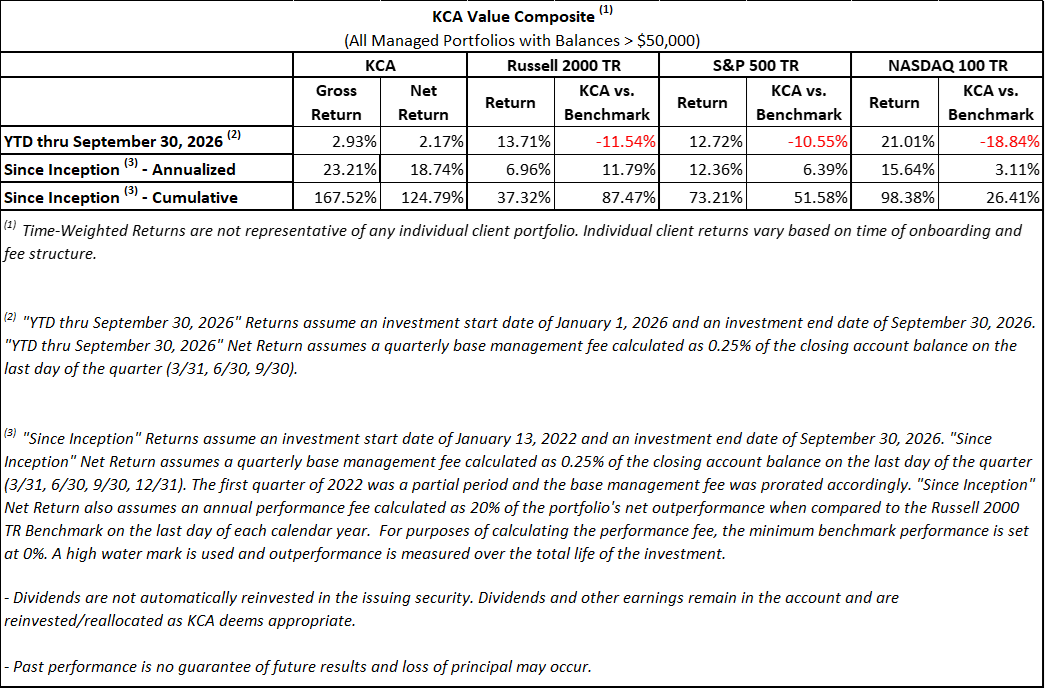
Kingdom Capital Advisors’ KCA Value Composite declined -15.52% net of fees in the third quarter. Year-to-date through September 30, 2026, the composite returned 2.17% net of fees. The first half of 2026 had been a historic stretch for small companies: the Russell 2000 TR (“Russell”) posted its best first-half performance since 1991. In the third quarter the Russell declined -7.23% while the S&P 500 TR and Nasdaq 100 TR increased. The primary trigger was interest rates, and investors fled into the perceived safety of the largest companies. That backdrop explains part of our quarter, but not all of it. The difference is concentrated in two positions, which I'll address below.
Despite this drawdown, we have compounded at 18.74% net annualized since launch in January 2022, ahead of all the major indices, representing approximately 87 percentage points of cumulative net outperformance against the most comparable Russell. Returns vary by account due to rounding, account size, and timing of deposits or withdrawals.
Our top contributors this quarter were Core Natural Resources (CNR) and Scully Royalty (SRL). Our largest detractors were Entravision Communications (EVC) and Beasley Broadcasting Group (BBGI).
Setbacks
We reversed most of our year-to-date gains between August and September. The good news is few of our quarterly losses were realized and we consider these temporary headwinds. We are not immune to permanent impairments at KCA, but the recent decline is a product of falling stock prices despite the underlying companies performing as we expected.
Harkening back to Q2 of last year, we pointed out how prior drawdowns have played out:
Apr ’22 to Sep ’22: KCA declined 11%, recovering to new performance highs by Jan ‘23
Jan ’23 to May ’23: KCA again declined 11%, reaching new performance highs by Jul ‘23
Nov ’24 to Jun ‘25: KCA declined 15% (and reached new performance highs merely three months later)
Past performance is not indicative of future results. But history has shown our strategy is volatile; drawdowns happen regularly, and recovery is possible. We remain optimistic that we own companies that will recover.
Entravision Corporation (EVC) and Beasley Broadcasting Group Inc (BBGI) combined for 80% of our quarterly decline (-12.5% of the -15.5%):
EVC -50% since August 10th
After hours on August 10th, KCA was making new highs as EVC traded up to ~$15/share after delivering results in line with our expectations. During the Company’s conference call, they shared that Q3 revenue in their AdTech business (Smadex) was unlikely to exceed Q2, but that revenue in Q3 and Q4 would each exceed the prior year by 100%. The sequential revenue decline in Smadex from Q2 to Q3 spooked investors and the stock price has subsequently halved. While we can’t control investor sentiment, we can control our understanding of the business and its performance. Mike and I have spent time identifying customers at Smadex which has strengthened our resolve that the Company has separated themselves as a transparent platform offering high returns on ad spend.
Most companies of this size and quality have investment banking research that connects the dots for investors, but Entravision does not. That creates the opportunity for which Kingdom Capital exists and we remain confident the market is misunderstanding the strength of Smadex’s offering. They have developed significant leadership in the growing Connected TV (“CTV”) space, deepening their moat. There are significant trends emerging in ad tech around transparency, on which Smadex has built their business model. This is a very good business that the market is currently offering at a very attractive price. We view the current EVC valuation as follows: the business should be net debt-free at year end, with a couple hundred million of value attached to their legacy broadcast assets. That implies Smadex is being valued at 3-4x run rate earnings power, which is the price one usually pays for a broken and/or dying business.
Don’t take our word for it, since EVC reported in August they have participated in public events with AppLovin’s Adjust, PubMatic, Magnite, and co-authored a CTV white paper with Moloco and Vibe.co. Investors seem concerned with the viability of Smadex, but leading ad tech industry players appear happy to publicly associate with this rising star. We are glad industry players and customers are happy, and now we wait for the stock price to follow.
BBGI -62% since August 4th
Our other main source of decline was BBGI, which declined significantly in the same timeframe. My thesis was simple: the company needs to sell about $100m of assets within a year, or the Beasley family loses control of the company. Unfortunately, the Beasleys decided the first order of business was to sell $5m worth of equity before announcing significant asset sales. I didn't expect them to issue equity before selling assets, and it cost us this quarter. The good news is they maxed out issuable shares under “baby shelf” rules and still need to sell about $100m of assets. While this approach led to a lot of indiscriminate selling of the stock from other disappointed shareholders, Management still needs to act to avoid losing their family's business and source of income. We estimate the remaining Beasley radio assets are worth $200-400m, with at least $50m more of real estate value, against a current enterprise value of about $150m. Even at the low end, the stock would be worth 3-5x the current price. our observations continued to support our view that consumer demand for the brand remains healthy. For what it’s worth, Mikal Bridges appears to be an enthusiastic customer:
Positioning
It was a relatively quiet quarter for our other top positions. United Natural Foods (UNFI) and Magnera (MAGN) continue to execute their business plans and trade at cheap valuations despite being the largest players in each of their niches. We expect them both to continue to inflect their earnings power higher in the coming quarters, ahead of street expectations. Net Lease Office Properties (NLOP) again declined along with the broader real estate sector as interest rates rose. While a cold commercial real estate market can slow down NLOP sales, they are unique among REITs with minimal overhead, net cash, and a flexible mandate to sell properties as they pursue liquidation.
There is no shortage of macro market narratives: interest rates, consumer strength, inflation, energy, AI, and midterm elections. We analyze our exposure to each of these themes, with the goal of weathering volatility while waiting for catalysts to outperform. The stocks don’t always respond the way we expect in the short-term, but we seek to build a portfolio that will remain resilient over the long-haul in many scenarios:
Rates and inflation increase is beneficial to our Mount Logan Capital (MLCI) investment, where the company has put significant efforts into cleaning up their earnings profile and the stock has barely increased. It also benefits UNFI, who earns positive carry on inventory in a thin-margin business and raised their guidance for the year. Meanwhile, lower rates should benefit NLOP’s remaining asset sales.
Consumer trade-down to grocery from restaurants benefits UNFI, and strengthening consumer trends would be a tailwind to our Magnera and a.k.a. brands (AKA) positions, along with Smadex’s ad business.
Core Natural Resources (CNR) has meaningful positive exposure to rising energy prices from ongoing global conflicts, while also seeing sustained power demand from the domestic AI trade and coking coal demand due to steel protectionism. Even UNFI and Magnera who are exposed to rising input prices from energy and diesel are well-hedged, providing them advantages over smaller peers.
Midterm ad spending should be a direct tailwind for EVC and BBGI, with competitive races in many of their coverage markets. We generally avoid hot-button sectors that may come under further scrutiny depending upon how the midterms resolve.
As always, we also maintain a basket of special situations we expect to perform in an uncorrelated fashion from the broader market. We expect Enviri (NVRI) to continue their efforts to clean up the remaining business after selling Clean Earth and think it’s worth double the current share price by 2028. We also expect potential strategic news soon from Monro (MNRO) after Carl Icahn accumulated a third of the outstanding shares at prices higher than what we just paid. And we anticipate news on Harbor Diversified (HRBR) by year end, who we estimate has far more cash than the current market valuation after selling all their assets.
Closing Thoughts
Historically, drawdowns are the most common time for clients to withdraw money, and Mike and I understand the pain of seeing a lower number in your accounts after the fresh highs only a couple months ago. We would point to our history of recovering and remind you all that we feel every drawdown acutely. We remain focused on protecting your capital and seeking the best ways to earn good returns going forward. As always, thank you for your continued trust and partnership. Please do not hesitate to reach out with any questions.
Sincerely,
David Bastian
Chief Investment Officer
DISCLOSURES
This document is not an offer to invest with Kingdom Capital Advisors, LLC (“KCA” or the “firm”).
The statements of the investment objectives are statements of objectives only. They are not projections of expected performance nor guarantees of anticipated investment results. Actual performance and results may vary substantially from the stated objectives. Performance returns are calculated by Morningstar.
An investment with the firm involves a high degree of risk and is suitable only for sophisticated investors. Investors should be prepared to suffer losses of their entire investments.
Certain information contained in this document constitutes “forward-looking statements,” which can be identified by the use of forward-looking terminology such as “may,” “will,” “should,” “expect,” “anticipate,” “target,” “intend,” “continue” or “believe,” or the negatives thereof or other variations thereon or comparable terminology. Due to various risks and uncertainties, actual events or results or the actual performance of the firm described herein may differ materially from those reflected or contemplated in such forward-looking statements.
This document and information contained herein reflects various assumptions, opinions, and projections of Kingdom Capital Advisors, LLC (“Kingdom Capital Advisors” or “KCA”) which is subject to change at any time. KCA does not represent that any opinion or projection will be realized.
The analyses, conclusions, and opinions presented in this document are the views of KCA and not those of any third party. The analyses and conclusions of KCA contained in this document are based on publicly available information. KCA recognizes there may be public or non-public information available that could lead others, including the companies discussed herein, to disagree with KCA’s analyses, conclusions, and opinions.
Upon request, KCA will furnish a list of all prior securities discussed in our publications within the past twelve months to include the name of each security discussed, the date and nature of each discussion, the market price at that time, the price at which the KCA acted upon the discussion (if at all), and the most recently available market price of each security.
Funds managed by KCA may have an investment in the companies discussed in this document. It is possible that KCA may change its opinion regarding the companies at any time for any or no reason. KCA may buy, sell, sell short, cover, change the form of its investment, or completely exit from its investment in the companies at any time for any or no reason. KCA hereby disclaims any duty to provide updates or changes to the analyses contained herein including, without limitation, the manner or type of any KCA investment.
Positions reflected in this letter do not represent all of the positions held, purchased, and/or sold, and may represent a small percentage of holdings and/or activity.
The S&P 500 TR, Russell 2000 TR, and NASDAQ 100 TR are indices of US equities. They are included for information purposes only and may not be representative of the type of investments made by the firm. The firm’s investments differ materially from these indices. The firm is concentrated in a small number of positions while the indices are diversified. The firm return data provided is unaudited and subject to revision.
None of the information contained herein has been filed with the U.S. Securities and Exchange Commission, any securities administrator under any state securities laws, or any other U.S. or non-U.S. governmental or self-regulatory authority. Any representation to the contrary is unlawful.
This information is strictly confidential and may not be reproduced or redistributed in whole or in part.
